The Machine Readings · Paper I
A sub-series of the Public Doctrine Series
The Seven-Day Horizon
Why a trading ledger reports its successes in hours and its failures in weeks, and what that does to every early verdict on a new rule
Dr. Glen Brown · President & CEO, Global Financial Engineering, Inc. and Global Accountancy Institute, Inc.
GFE-PUB-MR-20261026-A-CS · 26 October 2026
How to read this paper. The Machine Readings reason from a trading machine’s own records rather than from commentary on markets. Every claim of fact carries one of three marks. [W] Witnessed: read directly from a ledger or journal the machine wrote. [D] Derived: computed from witnessed figures, or from stated mathematics, by a method this paper gives. [I] Inferred: an interpretation the evidence supports but does not compel. A sentence without a mark is argument, not evidence.
About the case. The case in this paper is an illustration built from operating data. Figures have been altered so that no account, venue or period can be identified, and nothing here reports the results of any account. The mathematics, the design and the reasoning are unaltered.
I. The Reading
Every new rule arrives with a question attached to it, and the question is always the same: is it working? On the evening the reading was taken the question had a tempting answer. A new entry rule had governed the births of a small multi-asset book for six days. In that time it had produced 208 positions, of which 146 had already closed at their target and not one had been stopped out. [W] A rule with that record invites a verdict, and the verdict it invites is approval.
The machine’s own ledger declined to give it. Across the eighteen positions the book had lost to its stop since the present exit law took effect, not one had died younger than 6.9 days; the median age at death was 12.6 days. [W] The oldest position born under the new rule was under six days old. [W] The rule had not yet lived long enough to be asked the question. Its record contained no deaths for the same reason a class of first-year students contains no graduates.
That observation is the reading, and this paper is about why it is not an accident of one book or one week. I shall argue that it is a property of an entire family of designs, those that take small gains quickly and accept rare, larger losses slowly, and that the property is exact enough to be calculated before a single position is opened. In such a design success and failure run on different clocks, and the ratio of the clocks is set by the square of the ratio of the distances to target and to stop. Until the slower clock has run, an early ledger is not a small sample of the truth. It is a biased one, and the bias has a known direction: it flatters.
The reading is therefore not a judgement on the rule. It is a judgement on when the evidence can speak, on what can honestly be read before it does, and on what a machine must measure instead of waiting. Those three questions organise what follows.
II. The Mechanism
Two resting orders and nothing else
Every position in the case is born with two orders resting at the venue. The first is a bank, a take-profit placed a small fraction of a daily price range from entry. The second is a death stop, placed several daily ranges away on the other side. In the machine’s fastest lane the stop is about twenty-five times farther from entry than the bank; in its slower lanes the ratio narrows but remains large. [W] The design is general: anything that collects many small, quick gains against the risk of an occasional, larger loss has this shape, whether it is written as a trading rule, an option sold, a loan made or a policy underwritten.
There is no third exit. The firm’s doctrine forbids closing a position because time has passed: a position lives until price reaches one of its two levels, and only price decides which. [W] That prohibition is what makes the horizon this paper describes a clean object. A design that closes positions on a clock has two clocks of its own making; this one has only the market’s.
The geometry is a fair bet, by construction
A definition first, because the paper rests on it. By a fair walk I mean a price whose expected future value, given everything known now, equals its present value, judged against a position carrying a fixed bank and a fixed stop. Mathematicians call such a price a martingale, and the older name for it is a fair game. A fair walk is not quite a random walk. A random walk requires each move to be independent of the last and drawn from the same distribution, and it may drift; a fair walk may cluster its volatility and fatten its tails, but it may not drift. The distinction divides the results of this paper into two classes. Those about money, what the geometry can and cannot earn, need only fairness and hold almost whatever the market’s texture. Those about time, how long banks and deaths take to arrive, need the stronger assumptions of a random walk, and are calibrated estimates rather than theorems; whether real prices are random walks at all has been disputed since Lo and MacKinlay’s variance-ratio tests of 1988. [I]
Let the bank lie a distance b above entry and the stop a distance D below, both measured in daily ranges, and suppose for the moment that price has no drift. The probability that such a price touches the far level before the near one is the oldest result in the theory of chance, the gambler’s ruin: b ÷ (b + D). For the fastest lane, with b = 0.203 and D = 5.00, it is 3.90 per cent. [D]
Now ask a different question: what death share would leave the lane exactly at break-even? A bank pays b ÷ D of the risk unit R, here 0.0405 R, and a death costs one R. The break-even share p satisfies p × 1 = (1 − p) × b ÷ D, whose solution is p = b ÷ (b + D). [D] The two numbers are not merely close; they are the same expression. The machine’s edge instrument, which computes break-even from realised closes including their costs, independently printed 3.9 per cent for the same lane. [W]
This identity is the quiet centre of the design. The geometry by itself neither creates nor destroys expectancy. Placed in a market without drift, a position with this bank and this stop is a fair bet to the last decimal; costs make it a slightly unfair one. Every unit of edge the machine ever earns must therefore come from somewhere other than the geometry: from drift in the direction of birth, from structure in the markets it chooses to enter, from information. The academic literature reaches the same conclusion from the other side: Kaminski and Lo (Journal of Financial Markets, 2014) prove that under a random walk a stop-loss rule can only lower expected return, and that a stop earns its keep only when returns carry momentum. The resting orders are a null hypothesis written into the order book (the habit of judging a system by its governing condition rather than its latest outcome is the subject of The Fiscal Eigenvalue), and the realised death share is the market’s verdict on the machine’s information. That is why the edge instrument is defined as a ratio, break-even divided by the observed death share. A reading above one is information; a reading of one is the null; a reading below one is information pointing the wrong way. [I]
Two clocks
The same mathematics that sets the probabilities also sets the times, and here the asymmetry becomes stark. In a driftless walk with daily dispersion σ, the expected time to leave the corridor is b × D ÷ σ². But the average conceals two very different populations. The paths that bank do so on a timescale set by b², and the paths that die do so on a timescale set by D²: conditioned on death, the expected time to die is (L² − b²) ÷ 3σ², where L = b + D is the width of the corridor. [D] With a stop twenty-five times farther than the bank, the two clocks differ by roughly the square of twenty-five. Allowing for the long tail of first passage, the median bank and the mean death in this geometry differ by a factor of about seventy. [D] If banks arrive in hours, deaths arrive in weeks.
To turn that into dates one needs σ, which I express as a multiple c of the daily ATR(256) that measures the corridor. I do not assume c; I let the bank clock calibrate it. A simulation of the driftless walk on the fastest lane’s geometry places the median bank at 6.9 hours when c = 0.8 and at 4.7 hours when c = 1.0. [D] The book’s witnessed median time to bank on that lane is 5.9 hours, between the two. [W] The same band then predicts the death clock with no further freedom: a median age at death between 11.2 and 17.1 days, with one death in twenty arriving before 4.5 to 6.7 days. [D] The book’s witnessed deaths on that lane have a median age of 12.4 days, and none was younger than 6.9. [W] The clock of failure was predicted from the clock of success, and the prediction holds. [I]
Figure 1. The horizon of a fair walk
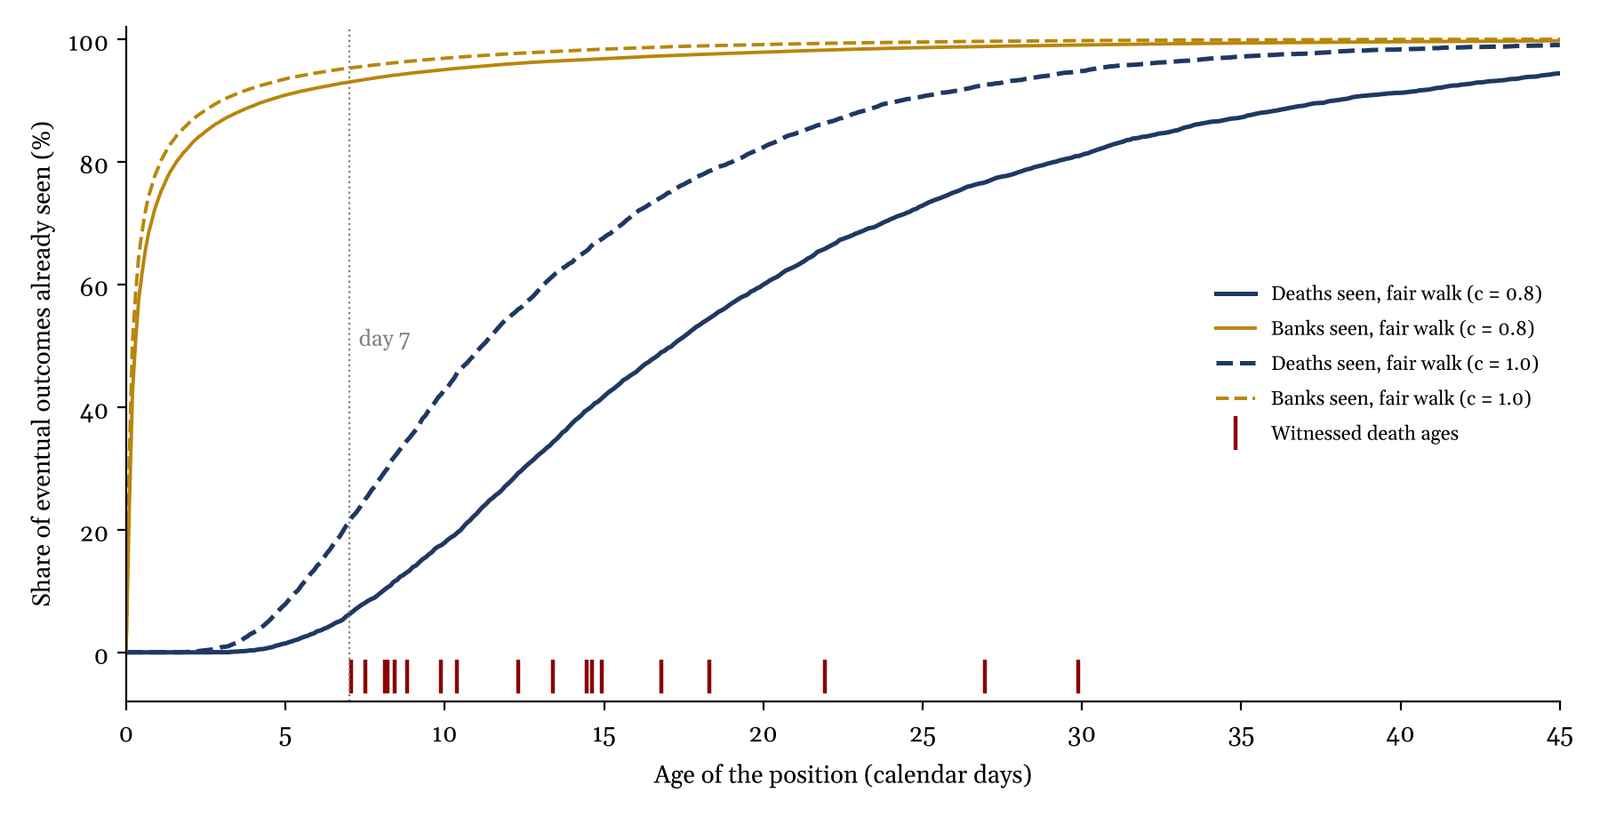
Share of eventual banks (gold) and eventual deaths (navy) already seen, by the age of the position, for a driftless price on the fastest lane’s geometry (bank 0.203, stop 5.00 daily ranges), at two calibrations of daily dispersion, c = 0.8 (solid) and c = 1.0 (dashed). Red ticks mark the ages at which the deaths in the case occurred. Simulation of 120,000 paths per calibration in five-minute steps; trading days converted to calendar days at seven to five.
Table 1. What a ledger can see, by age: share of eventual outcomes already recorded under a fair walk
| Age of position | Banks seen (c = 0.8 / 1.0) | Deaths seen (c = 0.8 / 1.0) | Death share a ledger would print | True death share |
|---|---|---|---|---|
| 3 days | 87% / 90% | 0.0% / 0.8% | ≈ 0.0% | 3.90% |
| 5 days | 91% / 93% | 1.3% / 8.7% | 0.1% to 0.4% | 3.90% |
| 7 days | 93% / 95% | 6.5% / 21.9% | 0.3% to 0.9% | 3.90% |
| 10 days | 95% / 97% | 18.9% / 43.9% | 0.8% to 1.8% | 3.90% |
| 14 days | 97% / 98% | 38.5% / 65.0% | 1.6% to 2.6% | 3.90% |
| 21 days | 98% / 99% | 64.2% / 85.0% | 2.6% to 3.4% | 3.90% |
| 30 days | 99% / 99.8% | 82.8% / 95.1% | 3.3% to 3.7% | 3.90% |
Derived. Columns two and three are shares of the outcomes each population will eventually produce. Column four rescales the simulated ratio of deaths to resolved positions to the continuous-time death probability of 3.90 per cent; the five-minute simulation itself overstates the eventual death share at about 4.9 per cent, because discrete sampling overshoots the near level, but the shape by age is insensitive to the step.
III. The Argument
First proposition: an early ledger flatters, and the flattery is deterministic
Read Table 1 down its fourth column. A cohort read at three days old prints a death share of essentially zero, not because it is safe but because its deaths are not yet due. At a week it prints less than a quarter of its true rate. At a fortnight it prints about half. Only after three to four weeks does the printed figure approach the truth. [D] None of this is sampling noise, which more data would wash out. It is a bias in a fixed direction, set entirely by the geometry and the calendar, and more data of the same age reproduces it exactly.
Accountants have known this shape for a long time under other names, and the parallels are exact rather than decorative. An insurer that booked only the claims reported in the first months of an underwriting year would report a profit the year will not earn; the reserve for claims incurred but not yet reported exists to correct precisely that. A lender’s loan vintages look clean until they season, which is why credit is judged on curves of losses by months on book and not on the losses of the most recent quarter. A seller of options records its premium on the day of the sale and its losses on the day of the move; Two Fears, One Discount Rate traces the same asymmetry of timing through the price of money itself. In each case the credits are frequent, small and fast, the debits are rare, large and slow, and the young book looks better than it is. [I] A trading machine with a near bank and a far stop belongs to the same family. Its open book is a reserve of deaths incurred but not yet reported.
The seven-day horizon of this paper’s title is therefore the floor of the problem, not the date of the answer. It is the age below which, on this geometry, deaths essentially cannot occur without a jump or a sustained one-way move. The date of the answer is later: the horizon at which most of the deaths a cohort will ever produce have been produced, which in this geometry lies three to four weeks after birth. [D]
Second proposition: silence before the horizon is not evidence
Apply the first proposition to the rule that prompted this paper. Take each of its 208 births, take the life each has actually lived to the close of the reading or to its bank, and ask how many deaths a rule that did nothing at all would have produced in those lives under a fair walk. The answer is between zero and two hundredths of a death. [D] The probability that such a useless rule would show a clean record is at least 98 per cent. [D] The zero in the ledger is not a weak signal in the rule’s favour. It is no signal at all.
What the young cohort can testify about is the clock that has already run. Measured against the cohort born under the same exit law in the week before the rule, at matched ages, the new rule’s births banked faster at every horizon: 58 per cent within a day against 50, 78 within two days against 55, 84 within three against 60. [W] That comparison is fair, because both cohorts have lived the ages being compared. The honest statement of the rule’s case is therefore exact and limited: it has proven faster banking, and on a book bound by a commitment ceiling the speed of a bank is the speed at which capacity returns. [I] It has not yet been asked about death, and will not be until its median member is a fortnight old.
Third proposition: deaths inside the horizon are information
If silence before the horizon says nothing, early deaths say a great deal. The cohort born under the same exit law in the week before the new rule offers the test. Given the lives its 182 births actually lived, a fair walk would have produced 0.3 to 0.8 deaths by the close of the reading. [D] The ledger recorded 5, six to sixteen times the fair-walk expectation. [W] All five were single equities. All five were born within a single session and died between 6.9 and 8.4 days old, on two consecutive sessions a week later. [W] A driftless walk does not produce five deaths in two sessions from one birth date at the very floor of its horizon. Something common to those names and those sessions did. [I]
The wider ledger points to what. Of the eighteen deaths since the exit law took effect, sixteen were single equities, and ten of them fell in two consecutive sessions of a quarterly reporting season. [W] At least three of the names died on the day of, or the first session after, their own scheduled results. [W] Diffusion sets the floor of the horizon; information decides who crosses it early. A company’s scheduled results are as knowable in advance as a payroll release, and for a single stock a larger event. [I] Whether a stop measured in daily ranges is the right instrument against a gap that is scheduled is a question for a later reading in this series.
The edge ledger is consistent with this account. Since the instrument began, the case book has banked about 320 times and died 19 times, a death share of 5.6 per cent against a break-even of 4.3. [W] Its fastest lane, the one Section II calibrated, stands at about 230 banks to 9 deaths, 3.8 per cent against 3.9: at, and fractionally better than, the null. [W] Its single equities stand at 7.5 per cent against 4.6. [W] Where the market behaves like a walk, the ledger reads like one. Where it carries scheduled discontinuities, the ledger reads them.
Fourth proposition: the research instruments inherit the bias
The bias is not confined to profit and loss. It reaches the instruments built to study the machine. The firm runs an observatory that follows every birth past its bank along a pure path, with no trail and no target, until the path either reaches 2.618 times its bank or meets the original stop. Of the paths that have ended, 105 of 110 reached 2.618 banks and five died first. [W] A further 152 paths are still alive. [W] Ninety-six per cent is a striking number, and it is an upper bound. The paths that have resolved are, by construction, the fast ones, and fast in this geometry means favourable; the slow paths still open are the population from which the deaths will come. [I] The same clock that flatters a young cohort’s death share flatters a young observatory’s success rate, and for the same reason. A research desk that forgets this will find, with great precision, the answer its sample was always going to give.
Fifth proposition: read distance consumed, not deaths recorded
If deaths cannot be read before the horizon, the machine must measure something that can. The martingale property of a driftless price supplies it. A position whose mark stands at m daily ranges from entry, with its bank at b and its stop at −D, will die with probability (b − m) ÷ (b + D). At birth that is the 3.90 per cent of Section II; as the mark falls toward the stop the probability rises in a straight line, reaching certainty at the stop itself. [D] The death that has not yet been recorded is already visible as distance consumed.
The machine’s edge instrument reads its open book in exactly this way. At the close of the reading the book’s hundred and thirty-odd open positions had carried a death chance of 4.8 per cent at birth and carried 30 per cent at their marks, which projects about 40 deaths among them. [W] That projection is the reserve for deaths incurred but not yet reported, and it is the correct reading of the book while the ledger is still young. It also disposes of a common misreading. Under a driftless market the marked equity is already the fair estimate of what the open book will realise; the projected deaths are the path by which the floating result of floating result becomes realised, offset by the banks the same positions will also make, and not a further loss on top of it. [D] What adds to it is carry, night by night; what subtracts from it is drift in the direction of birth. [I]
The same reasoning gives the earliest fair reading of the young cohort itself. Of the 60 positions still open from the new rule, 18 have at some point stood a quarter of R below entry and three half of R. Of the 27 still open from the cohort before it, 25 have stood a quarter of R below and 17 half of R. [W] The older cohort is older, so the comparison is not yet clean, but distance travelled toward the stop is the quantity that will become deaths, and it can be compared at matched ages long before the deaths themselves arrive. [I]
Read banks for speed. Read distance consumed for death. Read the death share only after the horizon has passed.
Put as doctrine, the argument reduces to that sentence. It asks nothing new of the machine. It asks the people who read the machine to stop treating the fastest-reporting outcome as the whole of the evidence.
IV. What Would Falsify This Reading
A reading that cannot be wrong is commentary. These are the observations that would show this one to be wrong, each stated so that the machine’s own records can settle it.
The floor of the horizon. The argument holds that, absent scheduled events, deaths on this geometry essentially do not occur before the fifth day. If deaths unconnected to any scheduled release repeatedly arrive inside five days, at a rate well above the zero to nine per cent of eventual deaths that Table 1 allows, the horizon is not set by diffusion and the first proposition fails. [I]
The young rule. When the new rule’s cohort has a median age past fourteen days, which on its birth dates falls about a fortnight after the reading, its death share at matched ages will be readable. If it stands at or above that of the cohort before it at the same ages, the faster banking recorded in Section III did not buy a lower rate of death, and the case made for the rule here fails with it. [I]
The reserve. If the driftless projection of the open book, scored cohort by cohort against the deaths that are eventually realised, systematically under-predicts them by more than the observed adverse drift of single equities explains, then distance consumed is not an adequate reserve and the fifth proposition fails. [I]
The calibration. Every date in this paper scales as 1 ÷ c². If the measured daily dispersion of the book’s universe proves to lie well outside 0.8 to 1.0 daily ranges, the shape of the argument stands but its dates move, and every horizon quoted here must be restated. [D]
The observatory. The fourth proposition predicts that the share of beyond-bank paths reaching 2.618 banks will fall as the 152 open paths resolve. If, once they have, the share remains above ninety per cent, the claim that the observatory flatters was overstated. [I]
V. The Case
The case is a small multi-asset book operated by a governed portfolio controller, read over a fortnight from its own ledgers and journals. Its exit geometry, described in Section II, was in force throughout. Three cohorts are distinguished. Positions born before that geometry took effect were managed under a different exit and are excluded from the fair-walk comparison. Positions born in the following week form the reference cohort. Positions born after that were admitted by a new entry rule that refuses two market states: quiet markets whose short-horizon behaviour is statistically indistinguishable from noise, and markets whose persistence has become stretched. Equity indices and grains are exempt from the first test. [W]
Table 2. The three cohorts at the close of the reading
| Cohort | Births | Banks | Deaths | Fair-walk deaths expected in lives lived | Note |
|---|---|---|---|---|---|
| Earlier exit regime | about 430 | — | 13 in the window | — | different exit; excluded |
| Reference cohort | 182 | 139 | 5 | 0.3 to 0.8 | deaths aged 6.9–8.4 d |
| New entry rule | 208 | 146 | 0 | about 0.00 – 0.02 | oldest under 6 d |
Witnessed counts; expected deaths derived by applying each birth’s observed life (birth to bank, or birth to the close of the reading) to the fair-walk death-time distribution of its own lane’s geometry, at c = 0.8 and c = 1.0. Figures altered for the case.
Table 3. Age-matched comparison: share of births banked within h hours, among births observed for at least h hours
| Horizon | New entry rule | Reference cohort | Deaths in either |
|---|---|---|---|
| 6 hours | 37% | 32% | 0 |
| 24 hours | 58% | 50% | 0 |
| 48 hours | 78% | 55% | 0 |
| 72 hours | 84% | 60% | 0 |
Witnessed. Figures altered for the case.
Read together, the two tables are the whole of the paper in miniature. The cohort that has lived long enough to be tested on death has been tested, and it died faster than a fair walk allows, at the floor of the horizon, in single equities during a reporting season. The cohort that has not lived long enough shows no deaths, which it would have shown whatever the merit of its rule, and it shows faster banking, which is a genuine finding because the ages at which it is measured have been lived. The verdict on the new rule is not withheld out of caution. It is withheld because the evidence that would decide it does not yet exist, and the machine has told us, to the day, when it will.
References
Doob, J. L. (1953). Stochastic Processes. New York: Wiley. The optional stopping theorem, on which the money results of Section II rest.
Fama, E. F. (1970). Efficient capital markets: a review of theory and empirical work. Journal of Finance, 25(2), 383–417. The fair-game model.
Kaminski, K. M. and Lo, A. W. (2014). When do stop-loss rules stop losses? Journal of Financial Markets, 18, 234–254.
Lo, A. W. and MacKinlay, A. C. (1988). Stock market prices do not follow random walks: evidence from a simple specification test. Review of Financial Studies, 1(1), 41–66.
Next in The Machine Readings
The Occupied Book: Paper II, on why a fair book is largely made of the positions that will fail, and why edge must be priced by the day.
Related reading in the Public Doctrine Series
The Fiscal Eigenvalue: why the slow mode of a system, not its fast one, decides whether it converges.
The Arithmetic of Escape: what a cure costs when its price is set by the slowest term in the arithmetic.
Two Fears, One Discount Rate: two fears priced through a single discount rate.
Download the PDF
About the Author
Dr. Glen Brown is President & CEO of Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. He is the architect of the GCPIAUT framework and the broader GATS-native proprietary capital doctrine. His work focuses on sovereign capital governance, algorithmic trading architecture, reserve-first compounding systems, and institutional financial engineering within closed proprietary environments.
Business Model Clarification
Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. operate as closed-loop proprietary institutions. They do not offer public investment products through the doctrines described herein, do not invite retail participation into their proprietary capital architecture, and do not present the GCPIAUT framework as a public collective investment scheme. The concepts discussed in this article are part of the firms’ internal intellectual and operating doctrine.
Risk Disclaimer
Trading and investment activity across foreign exchange, equities, futures, commodities, and digital assets involves substantial risk. Market conditions may change rapidly, and losses may occur. This article is provided for intellectual, institutional, and educational discussion only and does not constitute investment advice, an offer, a solicitation, or a recommendation to buy or sell any financial instrument or to participate in any investment structure.