The Instruments of Capital · Paper VII
Futures and Forwards
A contract to exchange later at a price agreed now. What it is a claim on, why its price has a shape, and why it is the only instrument in the series that is certain to end.
Dr. Glen Brown · Global Financial Engineering, Inc. · Global Accountancy Institute, Inc. · 14 November 2026 · GFE-PUB-IOC-20261114-E
About this series
The Instruments of Capital is a sub-series of the Public Doctrine Series. It sets out, one class at a time, every kind of asset a proprietary firm could trade, whether or not the firm trades it today. Each paper puts its subject through the six questions set in Paper I: claim, structure, return, carry, ending and risk unit. The case in Section VIII is an illustration built from operating data. Its figures have been altered and it reports no account’s results.
I. An agreement about later
A farmer with grain in the ground and a miller who will need grain in the autumn have opposite fears. One fears that the price will fall before the harvest and the other that it will rise. If they agree today on the price at which the grain will change hands in October, both fears are removed, and nothing has been bought or sold. That agreement is a forward contract, and it is very much older than any exchange.
The rice merchants of Osaka were trading standardised contracts of this kind on an organised market by 1730. The Chicago Board of Trade was founded in 1848 and in 1865 fixed the terms of its grain contracts and required a deposit from both parties as security for performance. With those two steps the forward became the future: a forward whose terms are set by an exchange, so that any buyer’s contract is identical to any seller’s, and whose performance is secured by money paid in advance.
The scale is now very large. In the first nine months of 2026 some 29.2 billion futures contracts changed hands on the world’s exchanges, 28 per cent more than in the same months of 2025, and 390 million contracts stood open at the end of September. The forward has not been displaced. In foreign exchange alone, forwards agreed directly between two parties turned over about $1.7 trillion a day in April 2025, against roughly $1.2 trillion three years earlier.
Every earlier paper in this series described something that can be owned: money, a debt, a share, a basket. This one describes an instrument that confers no ownership of anything. It is the sixth kind of claim named in Paper I, the contract, in its simplest form.
A future is not a thing held. It is a promise with a date on it, and the date is part of the price.
II. The claim
The holder of a forward or a future owns nothing until the contract matures. What the holder has is a right and an obligation together: to take or to make delivery of a stated quantity, at a stated price, on a stated day or within a stated period. The buyer is said to be long and the seller short, but neither has paid for anything, and the two positions are exact mirrors. For every contract held long one is held short, and the gains of one side are the losses of the other.
The difference between the forward and the future lies in who owes the performance. In a forward each party depends on the other. In a future the exchange’s clearing house stands between them, becoming the seller to every buyer and the buyer to every seller, and protects itself by taking a deposit from both and by settling every gain and loss in cash each day.
Table 1. The forward and the future compared
| Feature | Forward | Future |
|---|---|---|
| Terms | Whatever the two parties agree | Fixed by the exchange: quantity, grade, place and months of delivery |
| Counterparty | The other party | The clearing house |
| Security | As negotiated; often none until maturity | A deposit from both sides, with gains and losses settled in cash each day |
| Getting out | By agreement with the counterparty, or by an offsetting contract that leaves two claims standing | By an opposite trade, which cancels the position |
| Typical use | Currencies, interest rates, tailored commodity supply | Standard commodities, share indices, government bonds, short-term interest rates |
A third form is common in practice: a dealer’s contract that pays the change in the price of a named future. Its terms follow the future. Its counterparty is the dealer.
The third form in the note to Table 1 deserves attention, since it is how many participants meet futures at all. The holder of such a contract has no position on the exchange and no claim on the clearing house. The holder has a claim on a dealer, measured by reference to a contract the dealer may or may not hold. It is the future’s price inside a different wrapper, and Paper I’s warning applies: the wrapper decides who can fail.
III. The structure
An exchange lists each future for a series of delivery months, and each month is a separate instrument with its own price. There is no such thing as the price of copper futures. There is the price for December, the price for March, and so on along a line of dates that the market calls the curve.
The deposit, called initial margin, is a small fraction of the value the contract controls, commonly a few per cent. It is not a payment towards the goods and it is not the most that can be lost. At the end of each day the clearing house marks every position to the settlement price, takes cash from those who have lost and pays it to those who have gained. A holder who cannot meet that day’s call is closed out. This daily settlement is why the clearing houses have so rarely failed. It also means that a futures position that will prove right in the end must be financed, in cash, through every day on which it is wrong.
Contracts end in one of two ways. Some are settled by delivery: the short delivers the metal, grain or bond and the long pays for it. Others are settled in cash against a published price, as the share-index futures are. For contracts settled by delivery the exchange names a day, some time before the last trading day, from which a holder who is long may be called upon to accept the goods. Anyone who does not want them must be out before that day.
IV. The return
Since no money is paid for a future, the price of a future is not what anyone pays for an asset. It is the price at which the two sides are willing to exchange later. For anything that can be bought today and stored, that price is tied to today’s by a simple argument. A party who needs the goods in six months can buy them now and carry them, paying interest on the money and the cost of storage, and receiving whatever the goods yield in the meantime. The six-month price cannot stand far from today’s price adjusted for those three items, or one route would be plainly cheaper than the other.
For a share index the yield is the dividends, and the future stands above or below the index by the difference between interest and dividends. For a currency the yield is the foreign interest rate, and the result is the forward relation described in Paper II. For a government bond it is the coupon, set against the cost of financing the bond, as in Paper III. In each of these the future adds nothing that the underlying asset did not already offer. It is the same exposure with the financing built into the price.
Physical commodities are different, since the goods yield no income and yet are sometimes worth more in the hand than on a promise. A refiner short of crude oil cannot run a refinery on a contract for delivery next spring. When stocks are scarce, the nearby price rises above the later ones by more than the argument from storage allows, and the excess is the value of having the goods now.
What the holder of a future earns is therefore the change in the price of that contract, which is not the change in today’s price of the goods. The two differ by the slope of the curve. Keynes argued in 1930 that producers, anxious to sell forward, must as a rule accept a price below the one they expect, leaving a reward for those who take the other side. Gorton and Rouwenhorst, studying American commodity futures from 1959 to 2004, found that a diversified, fully collateralised holding had earned a return comparable to that of shares. Erb and Harvey, working at the same time, found that the average single commodity future had earned close to nothing, and that most of the return of a portfolio came from rebalancing among them. The disagreement has not been closed, and a reader should regard the long-run reward for holding commodity futures as contested.
V. The carry
The carry of a future is the slope of its curve. When later months stand above nearer ones the market is said to be in contango; when they stand below, in backwardation. A holder who wishes to keep a long position beyond the life of one contract must sell it before it ends and buy a later one, and this is called rolling. In contango the holder sells the cheaper month and buys the dearer, and as time passes the dearer month falls towards the level of the goods. In backwardation the reverse occurs and the roll is a gain.
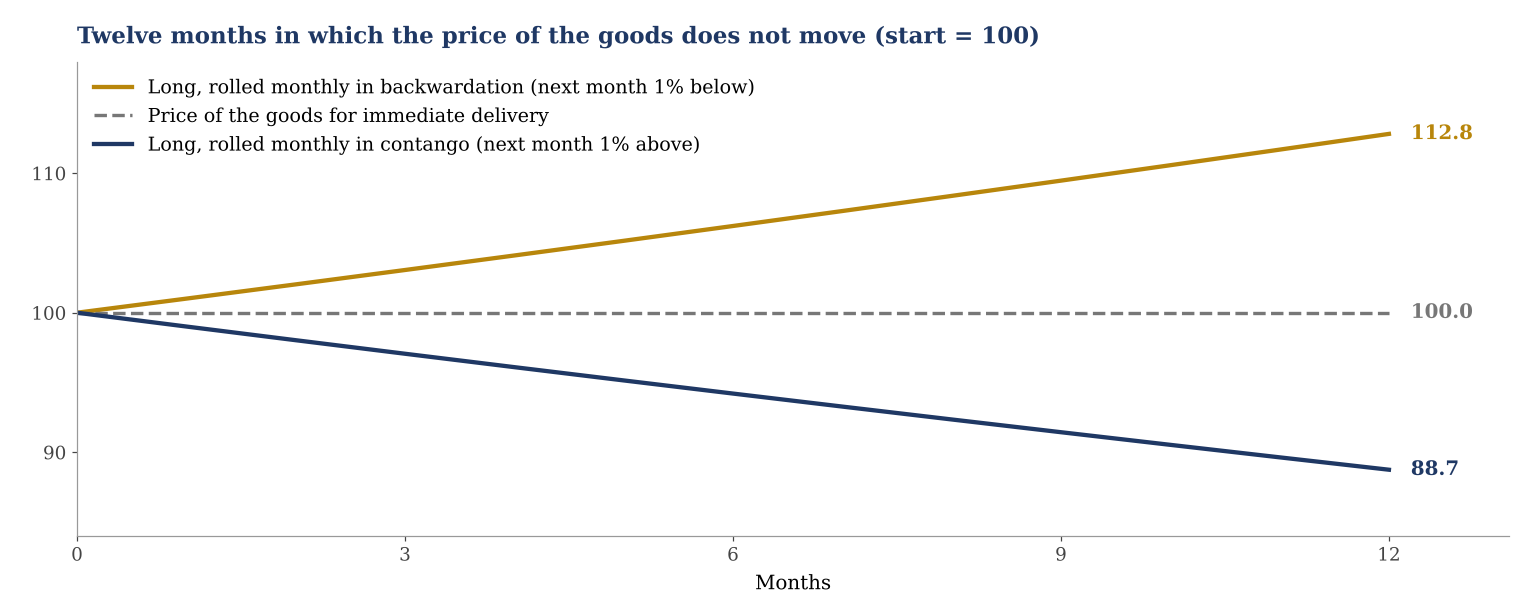
Figure 1. Illustration. The price of the goods for immediate delivery stays at 100 for twelve months. A long position rolled each month into a contract priced one per cent above the goods ends at 88.7. The same position rolled into a contract priced one per cent below ends at 112.8. Calculated; no market data.
Figure 1 isolates the effect. Nothing happens to the price of the goods in either case, and the two holders finish some 24 points apart. The carry appears on no statement as a charge. It is found only by comparing the return of the position with the change in the price for immediate delivery, and anyone who watches the second while holding the first will be surprised by it.
For the short the signs are reversed. A seller in a market in contango is paid to wait, and a seller in a backwardated market pays. The slope of the curve is, in this sense, the futures market’s equivalent of the interest differential in currencies: a known rate at which one side is compensated for holding the position while nothing else changes.
VI. The ending
Of all the instruments in this series, this is the only one that is certain to end, and on a day known from the start. A share may last a century, and a bond may be refinanced. A future has a last trading day printed in its specification, and in its final days the contract stops behaving like a claim on a price and starts behaving like an obligation to handle goods.
On 20 April 2020 the American crude-oil future for delivery in May settled at minus $37.63 a barrel. The contract was a day from its last and was settled by delivery at a storage hub whose tanks were nearly full. Holders who were long and had nowhere to put the oil had to find someone to take the obligation off their hands, and paid to do so. The price of oil for delivery a month later remained above twenty dollars throughout. What went negative was not the value of oil. It was the value of one contract’s ending.
The ending also governs anyone who intends never to reach it. In 1993 the American arm of the German group Metallgesellschaft had sold oil products to customers at fixed prices for up to ten years ahead and hedged the commitment with short-dated futures, rolled each month. When oil fell, the futures lost at once, in cash, under daily settlement. The offsetting gain on the customer contracts was real but lay years away. The parent closed the position at a loss of more than a billion dollars. Culp and Miller argued afterwards that the hedge was sound and was abandoned at the worst moment; others held that it was too large. Both readings agree on the mechanism: a position that had to be rolled and financed daily was matched against one that did not.
Finally, the rule book belongs to the exchange. In March 2022 the London Metal Exchange suspended its nickel market after the price more than doubled in two days and cancelled the trades of the morning. A contract’s terms include the power of the venue to change what has happened under them.
VII. The risk unit
The first error to avoid is measuring a futures position by its margin. The deposit says how much the clearing house wants as security against one day’s move. The exposure is the full value the contract controls: the price multiplied by the contract’s size. A position taken with a deposit of five per cent moves twenty times as fast, in proportion to the money put up, as the same position paid for in full, and its risk unit is the volatility of that full value.
The second matter is which month is held. Contracts near their end usually move more than distant ones, since news about present supply bears mostly on the present, and they become harder to trade as their last day approaches. The same commodity held in a nearby and in a distant month is two positions of different size.
The third is that contracts come in whole numbers. A single contract in a major commodity may control goods worth many tens of thousands of dollars, so that a book cannot hold less than one and cannot scale by fractions. The exchanges have answered this with smaller versions of their principal contracts, and the dealers’ form answers it by dividing the contract. Either way the minimum step is a fact about the instrument that the sizing rule must respect.
The fourth is the carry. Two positions of equal volatility are not equal if one is paid to wait and the other pays, and over holding periods of months the slope of the curve can outweigh the change in the price of the goods, as Figure 1 showed.
Table 2. The six questions answered for futures and forwards
| Question | Answer |
|---|---|
| Claim | A contract and not an asset: the right and duty to exchange later at a price agreed now. On a counterparty for a forward, on a clearing house for a future, on a dealer for a dealer’s contract |
| Structure | Separate instruments for each delivery month; a deposit that is a fraction of the value controlled; gains and losses settled in cash each day; delivery or cash settlement at the end |
| Return | The change in the price of the contract held, which is the change in the price of the goods plus or minus the slope of the curve; the long-run reward in commodities is contested |
| Carry | The slope of the curve: paid by the long in contango and earned in backwardation, and the reverse for the short |
| Ending | Certain and dated. The position must be closed, rolled or delivered, and the final days belong to those who can handle the goods |
| Risk unit | The volatility of the full value controlled, never the margin; adjusted for the month held, for the whole-number size of contracts and for the carry |
The answers hold for commodity, financial and currency contracts alike. They differ in the fourth row, where the slope is set by interest and income for financial contracts and by the scarcity of the goods for commodities.
VIII. The case
The following illustration is drawn from books that traded dated contracts in two forms: exchange futures held through a broker, and a dealer’s contracts on named delivery months. The rules that opened and closed positions were the same as for every other class and had first been written with instruments in mind that do not end.
The first lesson came early. A position in a livestock future was open when the contract reached its end. The venue closed the position itself, at its own time and at its own price. Every exit the book had prepared for that position was bypassed, since none of them knew the contract had a last day. The discovery was that the venue had a clock the book’s rules could not see.
A rule was written to take that exit back. A fixed number of days before a contract’s end, new positions on it are refused, and any position that is losing or has not yet had its stop moved to the entry price is closed at the market. Shortly before the end, everything remaining on the contract is closed. The rule deliberately does not roll. If the next delivery month deserves a position, it must earn one on its own evidence, as any new instrument would.
Some weeks later a second livestock contract was closed out by the venue all the same. The rule had tested the contract’s expiry date, and that date was still some way off. What the venue had done, days earlier, was to restrict the contract so that positions could be closed but not opened, as venues do when delivery approaches. The book had recorded that restriction each day and declined to open positions, and had not understood it as the beginning of the end. The rule was amended to treat a dated contract that the venue will only allow to be closed as already in its final period, whatever its expiry field says.
At a later weekly close one book held short positions in three agricultural contracts for the same delivery month, in the dealer’s form. The dealer’s own expiry dates for the three fell on three different days over the following two and a half weeks, each of them ahead of the corresponding exchange contract’s last trading day. The book was reading those dates and reporting each contract as outside the period in which the rule acts, which was correct on that day. This paper does not report what followed, which lay ahead of the date of writing.
Three points come out of the case. The ending of a dated contract is a property of the wrapper as well as of the contract: the dealer’s date, the broker’s cut-off and the exchange’s last day were three different days for what a list would show as one instrument. The signs that an ending has begun are not confined to the date; a change in what the venue permits is one of them. And a rule that is correct for instruments that do not end is not thereby safe for one that does. The fifth question of Paper I has to be asked of each instrument, and here its answer had to be built into the rules after the venue had answered it twice on the book’s behalf.
IX. What would falsify this reading
The relation between the future and the cost of carrying the goods is enforced by arbitrage and has failed where arbitrage could not be done: when storage was full, as in April 2020, or when the goods could not be borrowed. The paper’s claim is that the relation holds within the cost of carrying it out, and it would be refuted by a persistent gap in a market where storage and financing were freely available.
The claim that the slope of the curve is the carry is arithmetic for a price that does not move, and Figure 1 assumes exactly that. Whether the slope predicts the return in practice is an empirical question on which the studies cited disagree. If curves in contango were followed, as a rule, by rises in the price of the goods large enough to repay the roll, the carry would be an illusion. The evidence to date is against that, but it comes from a limited number of markets and decades.
The case rests on two closures by a venue and one amended rule, and its last part is unfinished. It shows that the ending was missed and how. It does not show that the amended rule is complete, and a third way for a contract to end that neither test anticipates would count against it.
A future obliges both sides. The instrument that gives one side the right without the duty is the option, and it is the subject of the next paper.
References
Black, F. (1976). The pricing of commodity contracts. Journal of Financial Economics 3(1–2), 167–179.
Commodity Futures Trading Commission (2020). Interim Staff Report: Trading in NYMEX WTI Crude Oil Futures Contract Leading up to, on, and around April 20, 2020.
Culp, C. L. and Miller, M. H. (1995). Metallgesellschaft and the economics of synthetic storage. Journal of Applied Corporate Finance 7(4), 62–76.
Dr. Glen Brown (2026). What an Asset Class Is; Money and Foreign Exchange; Government Debt and the Price of Time. The Instruments of Capital, Papers I, II and III. Public Doctrine Series.
Erb, C. B. and Harvey, C. R. (2006). The strategic and tactical value of commodity futures. Financial Analysts Journal 62(2), 69–97.
FIA (2026). Trends in ETD Trading, Q3 2026: global futures volume and open interest, January to September 2026.
Gorton, G. and Rouwenhorst, K. G. (2006). Facts and fantasies about commodity futures. Financial Analysts Journal 62(2), 47–68.
International Swaps and Derivatives Association (2026). Global FX Derivatives Market Overview: Size, Structure and Uses, citing the BIS Triennial Central Bank Survey, April 2025.
Keynes, J. M. (1930). A Treatise on Money, Volume II: The Applied Theory of Money. London: Macmillan.
Schaede, U. (1989). Forwards and futures in Tokugawa-period Japan. Journal of Banking and Finance 13(4–5), 487–513.
Related in the Public Doctrine Series
What an Asset Class Is: The Instruments of Capital, Paper I, which sets the six questions and names the contract as the sixth kind of claim.
Indices, Funds and Exchange-Traded Products: The Instruments of Capital, Paper VI, where the index future first appears as one of six ways to hold a basket.
Money and Foreign Exchange: The Instruments of Capital, Paper II, on the forward relation between two currencies’ interest rates.
Download the PDF
About the Author
Dr. Glen Brown is President & CEO of Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. He is the architect of the GCPIAUT framework and the broader GATS-native proprietary capital doctrine. His work focuses on sovereign capital governance, algorithmic trading architecture, reserve-first compounding systems, and institutional financial engineering within closed proprietary environments.
Business Model Clarification
Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. operate as closed-loop proprietary institutions. They do not offer public investment products through the doctrines described herein, do not invite retail participation into their proprietary capital architecture, and do not present the GCPIAUT framework as a public collective investment scheme. The concepts discussed in this article are part of the firms’ internal intellectual and operating doctrine.
Risk Disclaimer
Trading and investment activity across foreign exchange, equities, futures, commodities, and digital assets involves substantial risk. Market conditions may change rapidly, and losses may occur. This article is provided for intellectual, institutional, and educational discussion only and does not constitute investment advice, an offer, a solicitation, or a recommendation to buy or sell any financial instrument or to participate in any investment structure.