The Instruments of Capital · Paper IX
Swaps and the Over-the-Counter Contract
Two parties agree to exchange payments and nothing is bought. What a private contract is a claim on, what it is worth, and how it ends when one side cannot pay.
Dr. Glen Brown · Global Financial Engineering, Inc. · Global Accountancy Institute, Inc. · 14 November 2026 · GFE-PUB-IOC-20261114-G
About this series
The Instruments of Capital is a sub-series of the Public Doctrine Series. It sets out, one class at a time, every kind of asset a proprietary firm could trade, whether or not the firm trades it today. Each paper puts its subject through the six questions set in Paper I: claim, structure, return, carry, ending and risk unit. The case in Section VIII is an illustration built from operating data. Its figures have been altered and it reports no account’s results.
I. An exchange of payments
In 1981 a computer company held debt in Swiss francs and German marks that it wished to turn into dollars, and the World Bank wished to borrow in those currencies and found it cheaper to borrow dollars. An investment bank arranged for each to service the other’s debt. No loan was repaid and no bond changed hands. Two institutions simply agreed to make each other’s payments for a period of years. The arrangement is generally taken as the first modern swap.
The idea proved general. Any two streams of payments can be exchanged: a fixed rate of interest for a floating one, one currency’s interest for another’s, the return on a share for the cost of financing it, a regular premium for a payment if a borrower defaults. In each the parties agree a reference amount, called the notional, on which the payments are calculated and which, outside currency swaps, is never paid by anyone.
These contracts are made privately between two parties and not on an exchange, and the market in them is called over-the-counter. It is by a wide margin the largest market described in this series, if it is measured the usual way. At the end of 2025 the notional amount of over-the-counter derivatives outstanding was $844.6 trillion, of which interest-rate swaps were $545.0 trillion. The market value of all of those contracts, the sum that would change hands if every one were closed, was $22.8 trillion, or 2.7 per cent of the notional. Both figures are correct, and the distance between them is the first thing to understand about the instrument.
A swap is worth nothing on the day it is made. Everything it becomes is the difference between what was agreed and what happened.
II. The claim
A swap is a contract under which each party promises the other a series of payments. Neither has bought anything, and neither owns anything but the other’s promise. The claim is therefore of the sixth kind named in Paper I, and it has a feature the future and the listed option do not: unless the contract is given up to a clearing house, the party owed the money is exposed to the particular institution on the other side for the life of the contract, which may be thirty years.
The market has built three defences against that exposure. The first is a master agreement, a single contract governing every transaction between the two parties, under which all of them are valued and set against one another if either party fails, so that only one net sum is owed. The second is collateral: the party that is losing posts cash or securities to the other, usually every day. The third, required by regulators for the standard contracts since the crisis of 2008, is clearing, by which a central counterparty takes the place of each side as it does for a future.
Table 1. The principal over-the-counter contracts
| Contract | One side pays | The other pays | Equivalent to |
|---|---|---|---|
| Interest-rate swap | A fixed rate on the notional | A floating rate on the notional | For the receiver of the fixed rate, a bond bought with borrowed money |
| Currency swap | Interest and principal in one currency | Interest and principal in another | A loan in one currency funding a deposit in the other |
| Total return swap | The whole return of a named asset | A financing rate plus a margin | Holding the asset on borrowed money without owning it |
| Credit default swap | A regular premium | The loss if a named borrower defaults | Insurance on a bond, as in Paper IV |
| Contract for difference | The change in an asset’s price since opening | A financing charge each night | A total return swap with no fixed term, in small size |
Each contract reproduces a position that could be built from the instruments of earlier papers. None adds a source of return that was not already there.
III. The structure
The terms of a swap are whatever the parties agree, and that freedom is the reason the market exists. A company with a loan that resets every three months for seven years can obtain a swap that matches it to the day. No exchange lists such a contract.
In practice the terms are far from free. Nearly all swaps are written on standard definitions under the same form of master agreement, and the standard interest-rate and credit contracts are now cleared. What remains tailored and bilateral is a minority by amount and includes much of what has caused trouble.
One term deserves separate mention, which is the reference. A floating payment is calculated from a published rate, and a swap is only as sound as that rate. For three decades the reference for most of the world’s swaps was a rate compiled from banks’ own estimates of their borrowing costs. It was found to have been manipulated, and it was withdrawn; the last of its dollar settings ceased in June 2023, and hundreds of trillions of dollars of contracts had to be moved to rates based on actual overnight transactions. A contract can therefore outlive the number it is written on.
IV. The return
At the moment of agreement the two streams of a swap are set to be of equal value, and the contract is worth nothing to either side. That is not an accident of pricing. It is how the fixed rate is chosen. A swap begins at zero and acquires value only as the world departs from what was agreed.
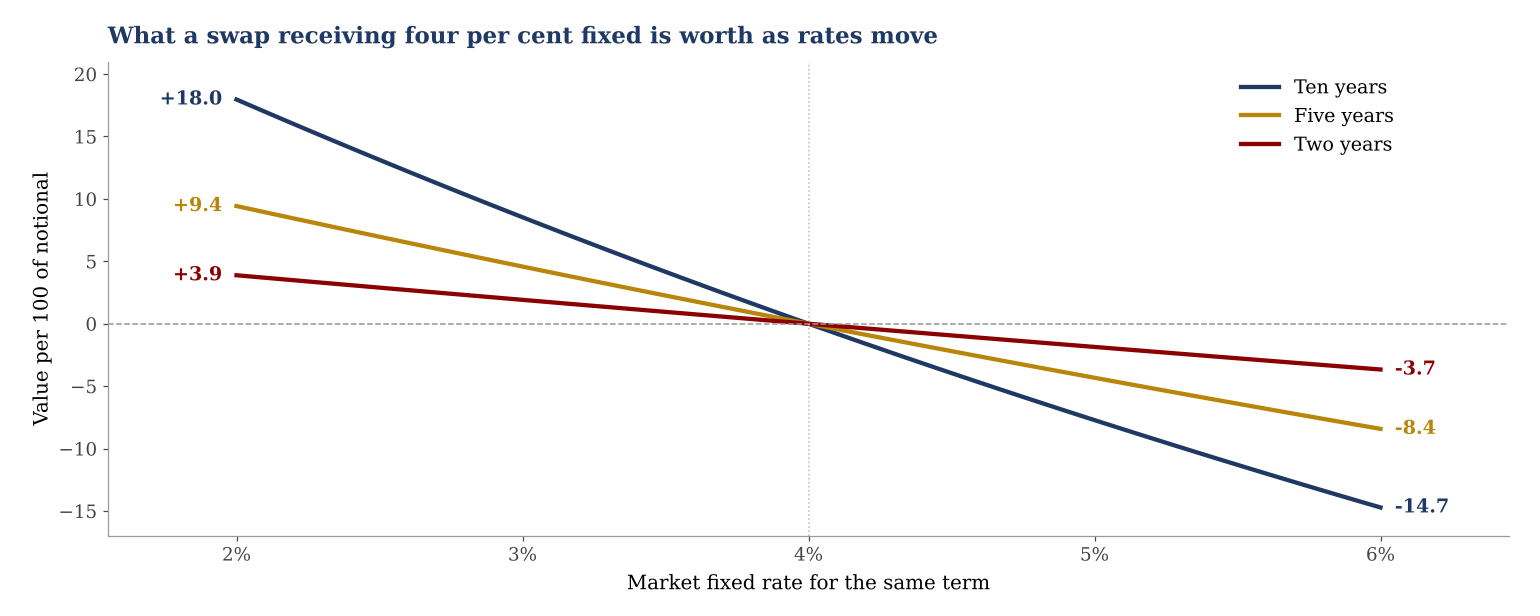
Figure 1. Illustration. The value, per 100 of notional, of a swap on which a fixed rate of four per cent is received and the floating rate paid, as the market’s fixed rate for the same term changes, for terms of two, five and ten years. At four per cent each is worth nothing. With the market at three per cent the ten-year swap is worth 8.53; at five per cent, minus 7.72. Calculated with annual payments; no market data.
Figure 1 shows the consequence for the plainest contract. The receiver of a fixed rate gains when rates fall and loses when they rise, in exactly the manner of the holder of a bond of the same term, and by an amount that grows with the term. Paper III’s account of duration applies unchanged. The swap is the bond’s interest-rate exposure with the bond removed.
This is true of the whole family, as the last column of Table 1 indicates. A swap does not offer a return of its own. It offers the return of some other position, without the purchase. The practical meaning of that is leverage. A party with a modest amount of collateral can take on the price exposure of a very large holding, and the only limit is what the counterparty will permit.
The notional and the market value now fall into place. The notional measures the size of the positions being imitated. The market value measures how far those positions have moved since the contracts were made. A market with notional of $844.6 trillion and value of $22.8 trillion is one in which very large exposures have, on average, moved by a few per cent from where they started.
V. The carry
The carry of a swap is the difference between the two streams while nothing changes. The receiver of a fixed rate of four per cent against a floating rate of three earns one per cent a year on the notional for as long as that remains so; the payer bears it. It is the same carry as that of a bond financed at the short rate.
For the contracts that stand in for ownership, the carry is the financing. The holder of a total return swap or a contract for difference receives the asset’s return and pays an interest rate plus the dealer’s margin, calculated on the full value of the position and not on the collateral posted. The charge is small each night and is levied whether the position gains or loses. On a position supported by collateral of five per cent, a financing rate of five per cent a year consumes a sum equal to the whole of the collateral in twelve months. Where the holder is short, or where the asset’s own yield exceeds the financing rate, the charge may become a credit.
VI. The ending
A swap ends at its stated maturity with a last exchange of payments, and most do. It may also be ended early, by agreement, on payment of its market value by whichever side is losing. The endings that concern this section are the ones in which a party fails.
When a party to a master agreement defaults, the other may terminate every transaction between them, value each at the cost of replacing it, and set the results against one another and against the collateral held. One net amount is then owed in one direction. The procedure was tested on the largest scale in September 2008, when a major investment bank failed with something approaching a million derivative transactions outstanding across several thousand counterparties. Close-out worked as designed where the documents and collateral were in order. Establishing the replacement cost of so many contracts in a disordered market took years.
In the same week an insurance group that had written credit default swaps on several hundred billion dollars of securities was called upon for collateral it did not have. None of the securities had yet failed to pay. The contracts required collateral as their market value moved, the value had moved, and the calls exhausted the group’s cash. It was rescued by the American government with an initial facility of $85 billion. The loss that ended the business was a demand for collateral, not a default on the thing insured.
Two later episodes have the same form. In March 2021 a private investment firm that had built very large positions in a few shares through total return swaps with several banks could not meet its collateral calls; the banks sold the shares they held as hedges and lost more than ten billion dollars among them, none having known the size of the positions held at the others. In September 2022 British pension funds that had used swaps and similar contracts to match their liabilities were called for collateral as gilt yields rose at unprecedented speed, sold gilts to raise it, and drove yields higher, until the central bank intervened. In each case the positions had not ended. The collateral had run out.
VII. The risk unit
The notional is not the risk unit of a swap, and neither is the collateral posted against it. The risk unit is that of the position the swap imitates. For an interest-rate swap it is the change in value for a given change in rates, which Figure 1 shows to be close to that of a bond of the same term. For a total return swap or a contract for difference it is the volatility of the full value of the asset referred to. Whatever rule would size the underlying position sizes the swap.
Two further quantities belong to the swap and not to the position it imitates. The first is the exposure to the counterparty: the amount that would be lost if the other side failed today, which is the contract’s current value less the collateral held, and which changes daily and can be nil or large. The second is the claim the contract may make on cash. A swap that is losing must be supported with collateral day by day, and a position that is sound to maturity can still fail if the cash to carry it there cannot be found. Every episode in the last section was of this kind.
Table 2. The six questions answered for swaps
| Question | Answer |
|---|---|
| Claim | A promise of payments from a named counterparty, or from a clearing house where the contract is cleared. Nothing is owned |
| Structure | Terms as agreed, on standard definitions under a master agreement; payments calculated on a notional that is not exchanged; a published reference rate or price |
| Return | None of its own: the return of the position imitated. Nil at inception, and thereafter the difference between what was agreed and what happened |
| Carry | The difference between the two streams; for contracts that stand in for ownership, the financing charge on the full value |
| Ending | Maturity, agreed termination, or close-out on default with all contracts netted. In practice the dangerous ending is the collateral call that cannot be met |
| Risk unit | That of the position imitated, never the notional or the collateral; with the exposure to the counterparty and the possible demand for cash added |
The answers hold for interest-rate, currency, equity, credit and commodity swaps and for the dealer’s contract for difference.
VIII. The case
The following illustration is drawn from multi-asset books that held their positions in shares, indices, commodities and currencies as contracts with a dealer, most of them contracts for difference. They held no interest-rate or credit swaps. The contract for difference is the last line of Table 1, and the case concerns the part of it that a price chart does not show.
The books opened each position on evidence about price, fixed a stop, and set a level at which a first profit would be taken. Positions were sized on the distance to the stop. The charge for financing was present from the first night, debited or credited to each position separately and visible in the account, but no test at entry weighed it against the profit the position was opened to obtain.
Its significance depends on how long a position is held, and these books did not close positions on the passage of time. At one weekly close a book held a number of positions that had been open for six to eight weeks and stood below their entry prices without having reached their stops. Each had been charged or credited every night of that period. For a position that reaches its first profit within days, the financing is a rounding error. For one that waits two months, it can be a material fraction of the profit the position was opened to obtain, and it accrues on the full value of the position while the position does nothing.
The books’ rules were amended in three respects. The financing accumulated on open positions was brought into the measure of capital against which the books’ limits are set, so that a slow drain could not sit outside the accounts the rules consult. The result of every closed position was recorded net of financing and commission, so that a position closed at its target after a long wait would be judged on what it actually earned. And a test was added at entry: a position is not opened unless the profit it aims at is worth a stated number of nights of its own financing charge. A position whose financing is a credit is never refused on this ground.
In the record examined for this paper the entry test was in force, and no refusal under it appears. The paper therefore reports the rule and the reason for it, and does not report how often it has changed a decision.
The point for the series is that the dealer’s contract was being treated as if it were the asset. It is a swap. One side of it is the asset’s price, and the books’ rules attended to that side with great care. The other side is a stream of financing payments, and until the rules were amended it was recorded but not weighed. The fourth question of Paper I, what the instrument pays or costs while nothing happens, has an answer for every wrapper, and for this wrapper the answer is charged nightly.
IX. What would falsify this reading
The paper’s central claim is that a swap has no return of its own and is in every case equivalent to a position in other instruments. This is enforced by arbitrage and has failed at the edges: since 2008 swap rates in several currencies have stood below the yields of government bonds of the same term for long periods, which the equivalence does not permit. The usual explanation is the cost of the balance sheet needed to do the arbitrage. The claim should be read as holding within that cost.
The claim about endings is that the dangerous event is the collateral call and not the default of the thing referred to. It rests on four episodes. A reader might answer that clearing and the margin rules introduced since 2008 have changed the matter. The episodes of 2021 and 2022 came after those reforms, which is some evidence that they have moved the difficulty and not removed it.
The case shows that a financing charge went unweighed and was then brought into the rules. It does not show what the charge cost, and it does not show that the entry test is set at the right level. A record in which positions held for long periods were closed at their targets and proved, net of financing, to have earned what was intended would count against the need for the test.
An option’s price was described in Paper VIII as a quotation of volatility. The next paper considers the contracts that allow volatility itself to be bought and sold.
References
Bicksler, J. and Chen, A. H. (1986). An economic analysis of interest rate swaps. Journal of Finance 41(3), 645–655.
Credit Suisse Group Special Committee of the Board of Directors (2021). Report on Archegos Capital Management. 29 July 2021.
Dr. Glen Brown (2026). What an Asset Class Is; Government Debt and the Price of Time; Credit; Options. The Instruments of Capital, Papers I, III, IV and VIII. Public Doctrine Series.
Duffie, D. and Zhu, H. (2011). Does a central clearing counterparty reduce counterparty risk? Review of Asset Pricing Studies 1(1), 74–95.
Financial Crisis Inquiry Commission (2011). The Financial Crisis Inquiry Report. Washington: U.S. Government Printing Office.
International Swaps and Derivatives Association (2026). Key Trends in the Size and Composition of OTC Derivatives Markets in the Second Half of 2025, from BIS OTC derivatives statistics.
Related in the Public Doctrine Series
What an Asset Class Is: The Instruments of Capital, Paper I, which sets the six questions and introduces the wrapper.
Government Debt and the Price of Time: The Instruments of Capital, Paper III, on duration, which an interest-rate swap reproduces without the bond.
Options: The Instruments of Capital, Paper VIII, on the contract that binds one side only.
Download the PDF
About the Author
Dr. Glen Brown is President & CEO of Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. He is the architect of the GCPIAUT framework and the broader GATS-native proprietary capital doctrine. His work focuses on sovereign capital governance, algorithmic trading architecture, reserve-first compounding systems, and institutional financial engineering within closed proprietary environments.
Business Model Clarification
Global Financial Engineering, Inc. and Global Accountancy Institute, Inc. operate as closed-loop proprietary institutions. They do not offer public investment products through the doctrines described herein, do not invite retail participation into their proprietary capital architecture, and do not present the GCPIAUT framework as a public collective investment scheme. The concepts discussed in this article are part of the firms’ internal intellectual and operating doctrine.
Risk Disclaimer
Trading and investment activity across foreign exchange, equities, futures, commodities, and digital assets involves substantial risk. Market conditions may change rapidly, and losses may occur. This article is provided for intellectual, institutional, and educational discussion only and does not constitute investment advice, an offer, a solicitation, or a recommendation to buy or sell any financial instrument or to participate in any investment structure.